What is start-up deduction?
The starter's deduction is an additional deduction for entrepreneurs who have not been self-employed for long. Those who meet the conditions may deduct the amount of the starter's deduction from their profits on top of the self-employed deduction. The scheme is designed to give starting entrepreneurs extra financial leeway in the build-up phase of their business. The starter's deduction can only be applied if there is an entitlement to the self-employed deduction.
Terms
Check these conditions for the tax year:
- You are entitled to self-employed deduction.
- In at least one of the five preceding years, you were not an entrepreneur for income tax purposes.
- In those five years, you applied the self-employed person's deduction a maximum of twice.
- In the calendar year and the five preceding years, there was no tax-free return from a private limited company.
Hours criterion
For regular self-employed deduction, you must meet the hours criterion . Keep a record of the hours you actually spend on your business, including bookkeeping and finding clients. If you start partway through the year, the 1,225-hour threshold is not reduced proportionally.
State pension age
If you had already reached the state pension age on 1 January, both the self-employed deduction and start-up deduction will be halved. If you reach that age later in the year, this will not result in a halving. The reference date and look-back conditions are in the official explanation of self-employed deduction for starters.
How high is the start-up deduction in 2026?
The regular start-up deduction amounts to €2,123 in 2026. This amount is equal to that of previous years. The following table provides an overview of the amounts:
| Year | Amount start-up deduction |
|---|---|
| 2023 | € 2.123 |
| 2024 | € 2.123 |
| 2025 | € 2.123 |
| 2026 | € 2.123 |
The start-up deduction comes on top of the self-employed deduction, which amounts to €1,200 in 2026. Together, these deductions can add up to €3,323 provided all conditions are met.
Start-up deduction for incapacity to work
This is a separate scheme with different conditions. Among other things, your right to a disability benefit and the reduced hours criterion count towards it. Depending on previous use in the five preceding years, the deduction is a maximum of €12,000, €8,000 or €4,000, never more than your profit. Check the terms and conditions in the event of incapacity for work.
How many years canyou apply the start-up deduction?
The look-back conditions determine whether you may apply the deduction. If you are entitled to it, the start-up deduction increases your self-employed deduction. You cannot claim the self-employed deduction in the same tax return year while saving the start-up deduction for later.
Overview: self-employment deduction & start-up deduction
Self-employed deduction forms the basis; starters' deduction is the extra increase if you also meet the look-back conditions. For both amounts, your age on 1 January is relevant. The example below shows the effect of the combination with the SME profit exemption.
Example application
Fictional example for 2026: you are an entrepreneur, have not yet reached the state pension age on 1 January, and meet all the conditions for the self-employed deduction and start-up deduction.
| Step | Amount |
|---|---|
| Turnover minus business expenses | €50,000 − €10,000 = €40,000 |
| Self-employment deduction and start-up deduction | €1.200 + €2.123 = €3.323 |
| Profit after entrepreneurs' allowance | €36.677 |
| SME profit exemption | 12.7% × €36,677 = €4,658.98 |
| Taxable profit | €32.018,02 |
The deduction of €3,323 reduces your profit; it is not the same amount as a tax credit. Your final income tax and Zvw also depend on other income, personal deductions and tax credits.
Do you have a salary as well as profit? Include both in your tax calculation. Our income tax calculator provides an estimate; check the tax year and the assumptions you enter.
Applying for start-up deduction in the tax return
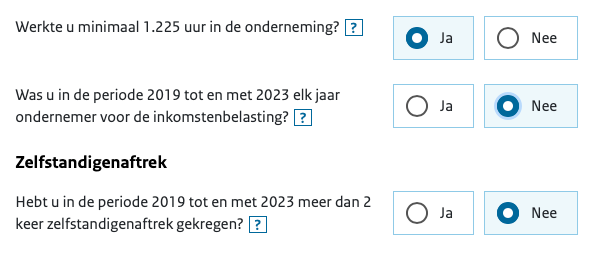
You process the start-up deduction in your income tax return. Answer the questions about entrepreneurship, hours and previous use of the self-employed person's deduction carefully. Also check the other conditions, such as a tax-free conversion from a private company (bv). If you are entitled to the start-up deduction, it will be added to the self-employed person's deduction.
Example from income tax return
Lower profit than deductions
If you are entitled to the regular self-employed person's deduction for starters, the self-employed person's deduction and the deduction for starters together may exceed your profit. This can result in a loss. Loss relief follows the rules for losses from employment and home ownership. This differs from the unrealised self-employed person's deduction for entrepreneurs without the deduction for starters.
Have a look at the overview of tax deductions for the self-employed. Would you like help with your administration and tax returns? Read what is included in the Van Passe package.
Frequently Asked Questions
How long does the start-up deduction apply?
The start-up deduction applies for up to three years within the first five years of entrepreneurship.
When do you apply the start-up deduction?
The deduction is applied in the years when all conditions are met and there is a right to self-employment deduction
What is the difference between self-employment deduction and start-up deduction?
The self-employed deduction is a general scheme for all entrepreneurs who meet the hour criterion. The start-up deduction is a temporary increase of it, specifically for nascent entrepreneurs.
What if the 1,225 hours is not met?
If the hour criterion is not met, both the self-employed deduction and the starter's deduction are forfeited. No use can then be made of these tax benefits.
How much discount does a starter get in the first three years?
There is no fixed tax credit for the first three years. In 2026, a €1,200 self-employed deduction and a €2,123 start-up deduction will together reduce the profit by €3,323 if you meet the conditions and have not yet reached the state pension age on 1 January. The tax saving depends on your full calculation.