What is the self-employment deduction?
The self-employed deduction is a fixed amount that you deduct from your profit subject to certain conditions. The deduction lowers your taxable profit; it is not a direct reduction of the same amount on your tax. How much you save depends on your personal tax calculation.
How high is the self-employment deduction?
In 2026, the self-employed deduction is €1,200. If you meet the hour criterion and the other conditions, you may deduct this amount from your profit before paying tax. This reduces your taxable income, which means you pay less tax at the end of the day. Exactly how big the benefit is depends on your profit and the tax bracket you fall into, but it can amount to hundreds of euros per year.
Phasing out: will the self-employed deduction disappear?
The self-employed deduction will be phased out in steps over the coming years. In 2024, the deduction was still €3,750, whereas by 2026 this has already been reduced to €1,200. According to the Tax Plan, the amount will decrease further to ultimately €900 in 2027. The aim of this is to narrow the tax gap between employees and the self-employed. For you as an entrepreneur, this means that it will yield progressively less benefit and that it becomes important to make optimal use of other deductible items.
| Year | Self-employment deduction |
|---|---|
| 2022 | € 6.310 |
| 2023 | € 5.030 |
| 2024 | € 3.750 |
| 2025 | € 2.470 |
| 2026 | € 1.200 |
| 2027 | € 900 |
What if your profit is lower than the self-employed deduction?
Without entitlement to the start-up deduction, the self-employed deduction is limited by your profit before entrepreneurial deductions. The unused amount is called unrealised self-employed deduction. You can offset this in the next nine years if you meet the conditions and have sufficient profit above the self-employed deduction in that year. The determined amount is stated on your assessment. With entitlement to regular start-up deduction a different loss rule applies.
Terms
You must be an entrepreneur for income tax purposes and meet the hours criterion. The Tax and Customs Administration assesses your entrepreneurial status based on all circumstances, such as independence and entrepreneurial risk. Chamber of Commerce registration alone is not enough.
You can also be entitled to this deduction after reaching the state pension age. If you had already reached the state pension age on 1 January, the amount is €600 instead of €1,200 in 2026, provided the conditions are met. If you reach that age later in the year, this does not result in a halving. View the official conditions and amounts for 2026.
How often can you use it?
You can apply the self-employed deduction every year as long as you meet the conditions. So there is no maximum number of times. However, the amount of the deduction will continue to decrease in the coming years, reducing the benefit.
Hours criterion self-employed deduction
In addition to a minimum of 1,225 entrepreneurial hours per calendar year, it generally applies that you spend more time on your business than on other activities. That second requirement does not apply if you were not an entrepreneur in at least one of the five preceding years. Only hours that you actually spend on your business count; keep a substantiated log. Read the full conditions of the hours criterion.
Applying self-employment deduction
You process the self-employed deduction in your annual income tax return. Fill in your business figures and the questions about entrepreneurship and hours correctly. Only apply deductions for which you meet the conditions. The SME profit exemption and the further personal tax calculation follow after the entrepreneurial deduction.
Example from income tax return
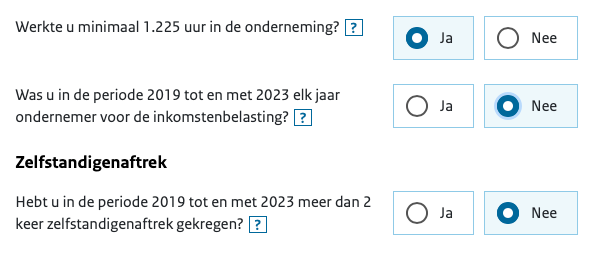
Overview of deductions: self-employment deduction & start-up deduction
The start-up deduction is an increase in the self-employed deduction. You must be entitled to the self-employed deduction, not have been an entrepreneur in at least one of the five preceding years and have applied the self-employed deduction a maximum of twice in those five years. Therefore, merely having a recently started business is not sufficient. You can read the remaining conditions at start-up deduction.
Sample calculation
Fictional example for 2026: you are an entrepreneur, have not yet reached the state pension age (AOW) on 1 January and meet the hours criterion. You are not entitled to the start-up deduction for self-employed persons.
| Step | Amount |
|---|---|
| Turnover minus business expenses | €50,000 − €10,000 = €40,000 |
| After self-employed deduction | €40,000 − €1,200 = €38,800 |
| SME profit exemption | 12.7% × €38,800 = €4,927.60 |
| Taxable profit | €33.872,40 |
This is not a calculation of your final income tax and Healthcare Insurance Act (Zvw) contribution. Other income, personal deductions and tax credits are also required for that.
Do you have a salary as well as profit? Include both in your tax calculation. Our income tax calculator provide an estimate; check the financial year and the entered conditions. In addition, look at which other deductions for the self-employed suit your situation.
Do you want to have your administration and tax returns taken care of? View what is included in the Van Passe package.
Frequently Asked Questions
What does the self-employed deduction mean?
It is a fixed deduction that reduces your profits and makes you pay less tax.
How high is the self-employed deduction in 2026?
In 2026, the self-employed deduction is €1,200.
How high is the self-employment deduction in 2025?
In 2025, the self-employed deduction will be €2,470.
How do I prove I meet the hours criterion for the self-employed deduction?
You need to keep records of hours with, for example, diaries, invoices and work reports.
What if you don't reach the 1,225 hours?
Then your right to the self-employed deduction and possibly the start-up deduction will be lost.
Does the self-employed deduction disappear altogether?
No. According to the scheduled phase-out, the self-employed deduction will drop to €900 by 2027. That is not a complete abolition.